


Ice Dams and Your Insurance Claim: What Minnesota Homeowners Should Know
Ice dams are a Minnesota winter ritual, and the leaks they cause are often covered. Here’s how to separate covered damage from maintenance and build a clean claim.
Independent claim appraisal · All 87 counties
Your insurer accepted the claim, but the payment won’t cover the repair. Minnesota Insurance Appraiser builds an independent, line-by-line valuation of the loss and carries it through the appraisal process written into your policy.
Covered isn’t the same as paid
Most short claims aren’t denied — they’re underscoped. A missed roof slope, steel siding that can’t be matched, ice and water shield left off the eaves, an interior ceiling written as “paint only.” A Minnesota Insurance Appraiser exists for that gap between an accepted claim and a repair that’s actually funded.
Appraisal solutions
11 services, one goal: a valuation of your loss that stands up. Start with an estimate review or bring us in once appraisal is demanded.
 01
We act as your named appraiser when the appraisal provision in your Minnesota policy is invoked by either side.
Learn more 02
Appraisal for houses, townhomes and cabins when the insurer’s estimate won’t cover a real Minnesota repair.
Learn more 03
Appraisal for association, townhome and commercial property claims where many buildings and owners share one policy.
Learn more 04
Appraisal for hail-damaged roofs, siding, gutters and soft metals across the Twin Cities and southern Minnesota.
Learn more 05
Appraisal for tornado, derecho and straight-line wind losses, from torn shingles to whole structures and fallen trees.
Learn more 06
Appraisal for sudden water losses such as burst pipes, appliance leaks and failed water heaters in Minnesota homes.
Learn moreThe process
The appraisal clause turns an open-ended argument into a defined process with a binding result on the amount. Here is how Minnesota Insurance Appraiser moves a file through it.
Read the full process guideWe read the policy, the insurer’s estimate and your photos, then tell you plainly whether appraisal fits.
Our own measurements and photos, then a line-item estimate priced for your Minnesota ZIP code.
Appraisal is demanded in writing, and Minnesota Insurance Appraiser is named as your appraiser.
We go line by line with the insurer’s appraiser. Many differences close at this stage.
Anything left goes to a neutral umpire. Signatures from two of the three set the amount of loss.
60-second gap check
Enter the two numbers you already have. A large difference is worth a call to a Minnesota Insurance Appraiser; a small one may close faster with a documented supplement.
The full claim gap & fee estimator adds appraiser and umpire fees and shows your break-even point.
Five claim regions
Hail in Plymouth, derechos near Mankato, lake-effect snow in Duluth, floods along the Red River. A Minnesota Insurance Appraiser has to know how each region’s weather shows up on a building — and in an estimate.
Seven counties, three generations of housing. Plaster-walled bungalows in Minneapolis and St. Paul, 1960s ramblers in the first-ring suburbs and townhome associations at the edges — often hit by the same spring hail line.
Communities: Minneapolis, St. Paul, Bloomington, Plymouth, Woodbury, Eagan, Blaine
Open country lets severe storms organize. The March 1998 St. Peter and Comfrey tornadoes and the May 2022 derecho both tracked through this region, where claims mix homes, machine sheds and small-town commercial buildings.
Communities: Rochester, Mankato, North Mankato, Owatonna, Faribault, Winona
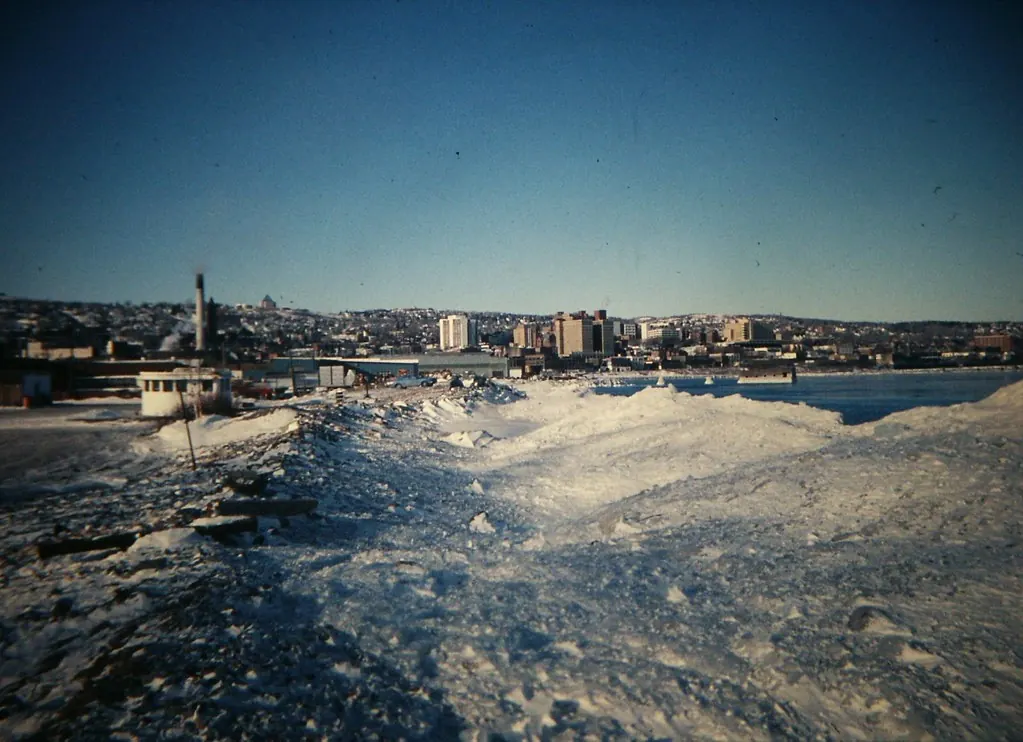
Lake-effect snow, steep hillside lots and seasonal cabins define claims here. The June 2012 Duluth flood showed how quickly water can overwhelm older storm systems.
Communities: Duluth, Hermantown, Two Harbors, Cloquet, Hibbing, Grand Marais
Lake country means seasonal properties that sit empty for months — the classic setup for an undiscovered frozen pipe or a snow-loaded porch roof.
Communities: St. Cloud, Sartell, Brainerd, Baxter, Little Falls, Alexandria
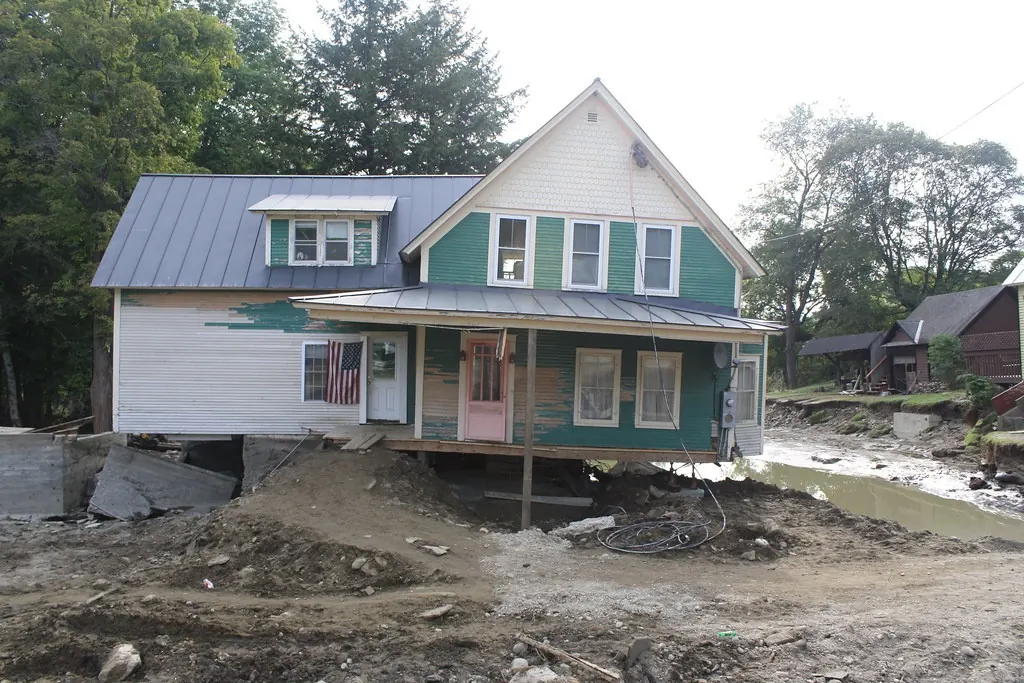
Flat terrain and a north-flowing river create a flood season unlike anywhere else in the state. Flood itself usually needs separate coverage, which makes sorting wind, water and flood damage a big part of claims here.
Communities: Moorhead, Dilworth, Fergus Falls, Detroit Lakes, Crookston
A year of claims
We see the same patterns every year. Knowing which season your damage came from helps date it, scope it and defend it.
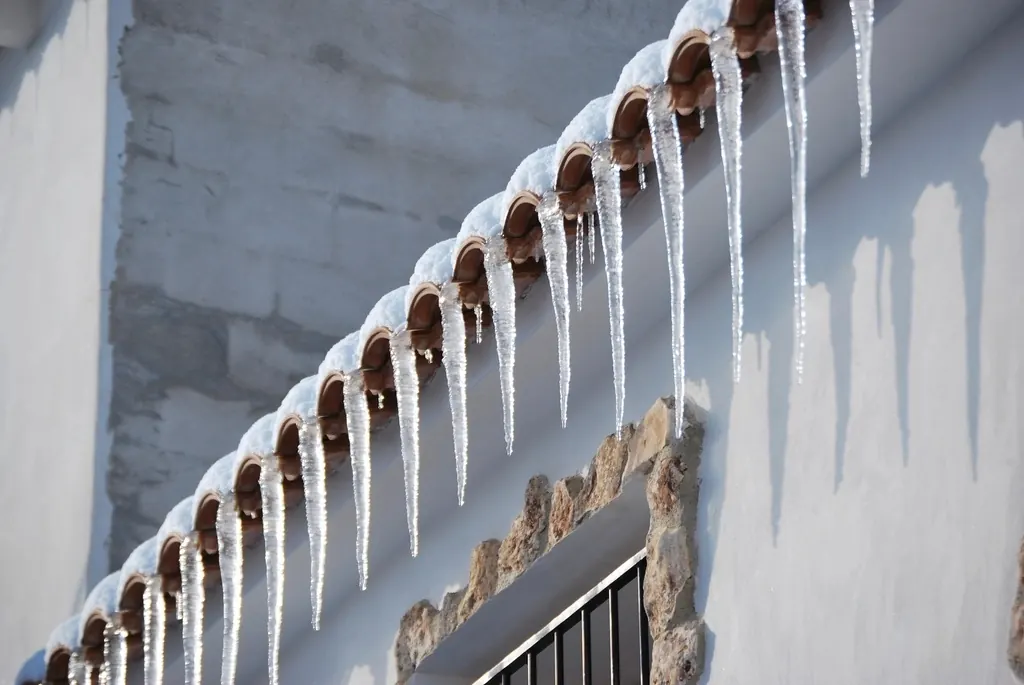
Meltwater backs up under shingles, pipes freeze in cabins and heavy snow tests older roofs.
Snowmelt finds every weak spot, and the first hail lines of the season roll through the metro and south.
Severe-weather season peaks: straight-line wind, tornadoes, hail and lightning fires.
Autumn storms and the last chance to find and document summer damage before snow covers the roof.
Free & private
Run the numbers before you call. Every tool works in your browser, and nothing you type is stored or sent.
 Calculator
Find the disputed amount, a projected award, your fees and the break-even point before you invoke appraisal.
 Calculator
Itemize your loss to see depreciation, the first check and the recoverable holdback after repairs.
CalculatorTurn a footprint and pitch into roof squares, waste and bundles to check the measurements on your estimate.
CalculatorConvert a wind/hail percentage deductible into dollars and compare it with a flat deductible.
PlannerMap notice, proof of loss, repair and suit-limitation dates from your date of loss, then export to your calendar.
 Checklist
Twelve yes-or-no questions that score your file and build a to-do list before appraisal is invoked.
CalculatorEstimate how much the snow and ice on your roof weigh in pounds per square foot — a Minnesota winter essential.
Service area
We inspect in person across the state. These are the communities where we handle claims most often.
Choosing help
Each solves a different problem. The right one first saves time and fees — and Minnesota Insurance Appraiser will point you elsewhere when appraisal isn’t the tool.
| Question | Minnesota Insurance Appraiser | Public adjuster | Attorney |
|---|---|---|---|
| Main job | Value the amount of loss | Handle & negotiate the claim | Legal disputes & litigation |
| Best moment | Coverage accepted, amount disputed | Early, from first notice | Denials, bad faith, deadlines |
| Result | Award signed by 2 of 3 | Negotiated settlement | Settlement or judgment |
| Decides coverage? | No | No | Argues it in court |
Questions
Straight answers on how appraisal works, what it costs and when it’s the wrong move.
We value property damage when you and your insurer agree the loss is covered but disagree on what it costs. As your appointed appraiser we inspect, build an independent estimate, work with the insurer’s appraiser and, if needed, present the remaining items to an umpire.
No. A public adjuster handles and negotiates the whole claim and is licensed by the Minnesota Department of Commerce. An appraiser works within the policy’s appraisal clause on one question: the amount of loss.
When coverage is accepted, you have the insurer’s itemized estimate, and the gap to your contractor’s number is meaningful — often more than about 10% or several thousand dollars.
An award signed by any two of the three panel members generally sets the amount of loss. It doesn’t decide coverage, which is why the file should be complete before appraisal starts.
In Minnesota, the state Supreme Court’s 2012 Quade v. Secura decision held that appraisers may decide causation as part of the amount of loss, while coverage questions stay with the courts. How that applies depends on your policy and facts.
Yes. We work statewide in all 87 counties, including Rochester, Duluth, St. Cloud, Mankato and Moorhead.
Learning center
Guides from the Minnesota Insurance Appraiser team on policy language, documentation and strategy.
Ice dams are a Minnesota winter ritual, and the leaks they cause are often covered. Here’s how to separate covered damage from maintenance and build a clean claim.
When an insurer says the damage is old or unrelated, can an appraisal panel weigh in? Minnesota’s Supreme Court gave a qualified yes in 2012.
Hail damage hides in more places than the roof. Use this checklist to document shingles, siding, gutters, screens and mechanicals before the adjuster arrives.
Before you sign off
A short review now can keep you from settling for less than the repair costs.
Start with a conversation
Tell us what happened and what the insurer offered. We’ll review it and tell you plainly whether appraisal is worth pursuing.

